Budgeting fails for many people not because they lack discipline, but because the process is tedious. Transactions pile up, categories are messy, bills arrive on different dates, and by the time a spreadsheet is updated the month is already half gone. This is why ai personal finance apps are gaining attention. They promise to watch the details continuously, sort spending automatically, warn you before money gets tight, and turn raw bank data into decisions you can actually use.
The promise is appealing, but it needs a clear boundary. An app can help you see patterns and follow a plan. It cannot know your values, repair a low income by itself, or guarantee investment results. The best approach is to treat AI as a diligent assistant for money management: fast at tracking and forecasting, useful for reminders, and always subordinate to your goals and judgment.
What AI Personal Finance Apps Actually Do
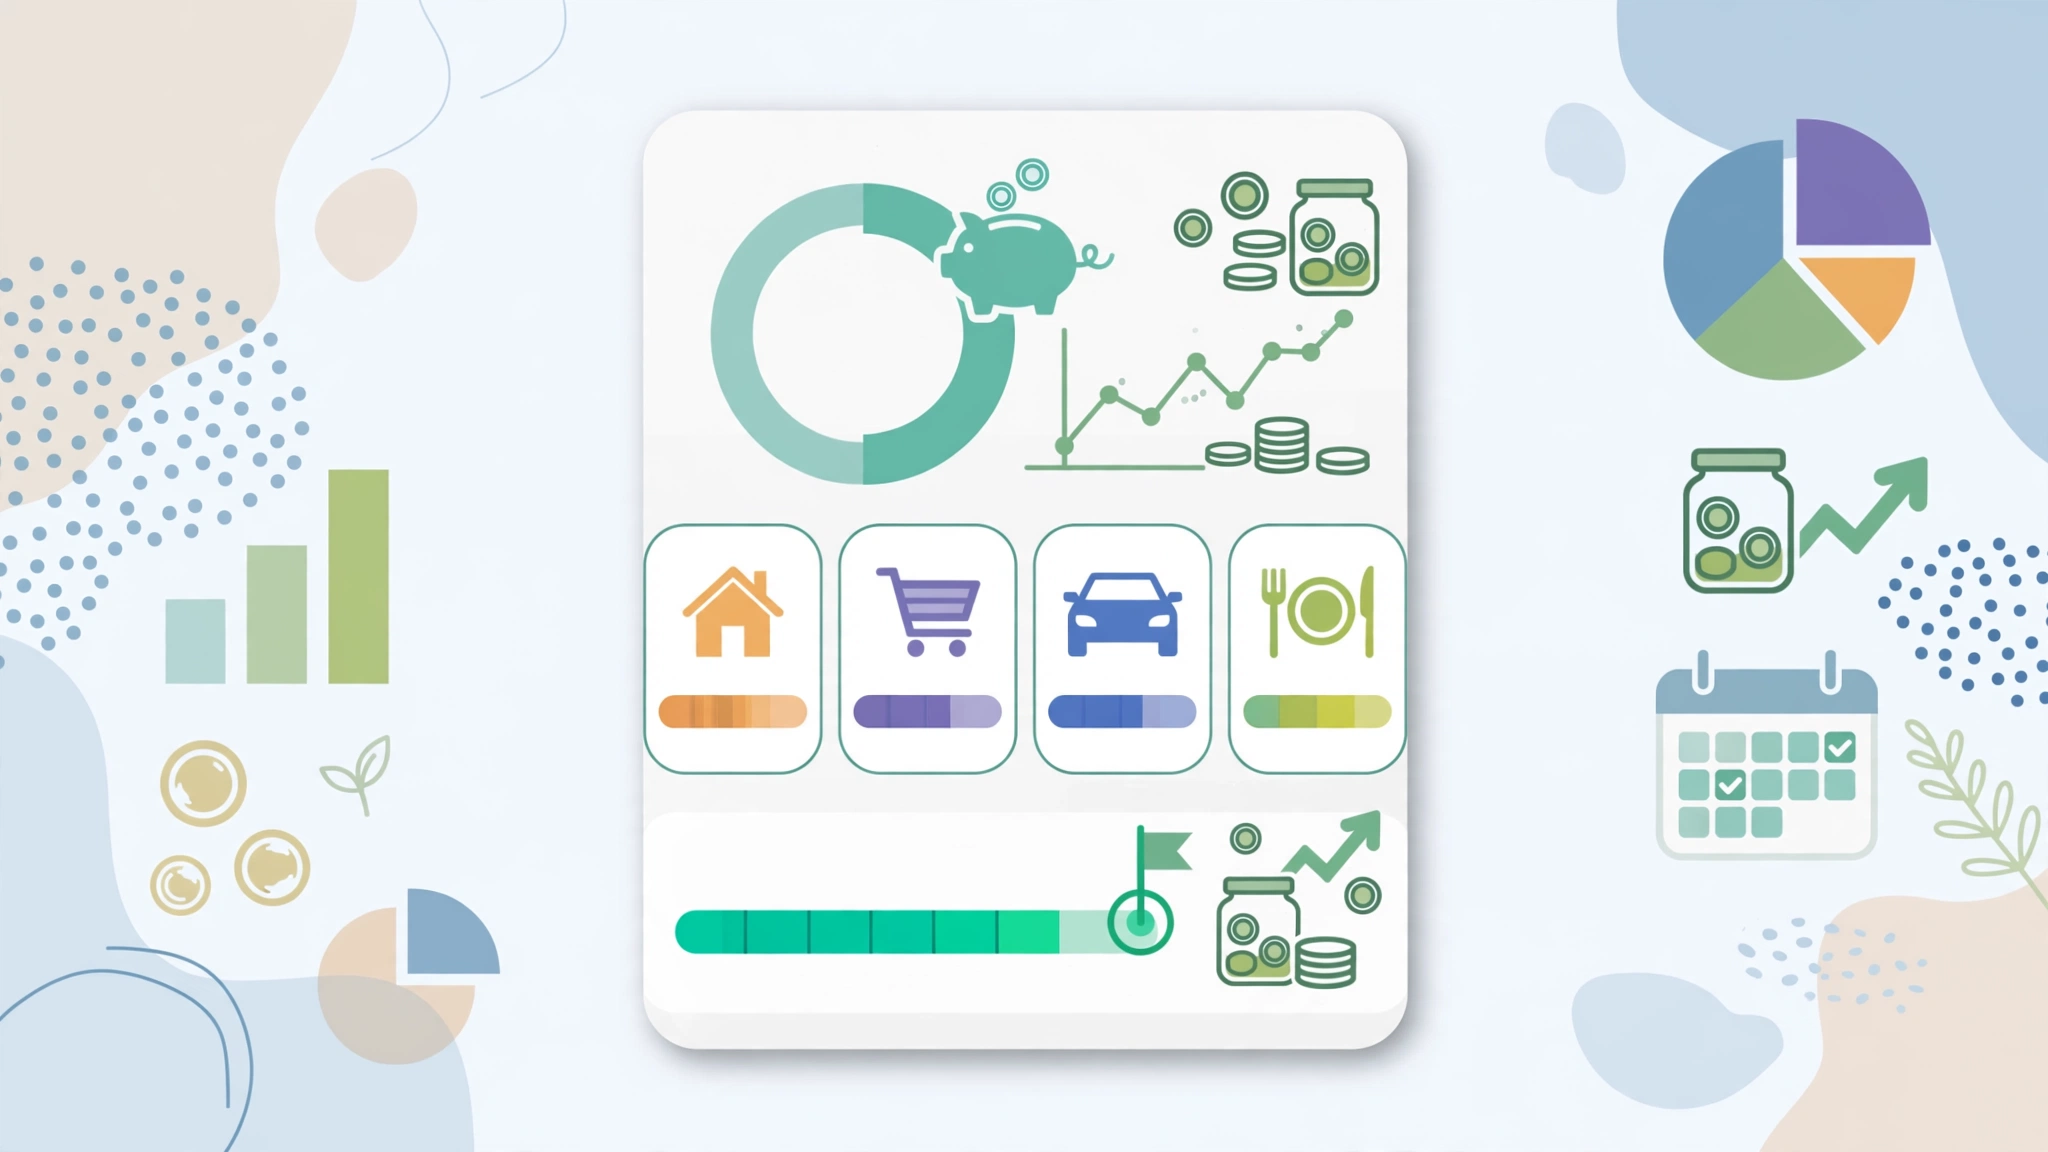
At their core, these apps connect to bank accounts, cards, and sometimes investment or loan accounts. They import transactions, categorize them, and build a picture of income, spending, balances, debts, and upcoming bills. AI features may label unusual purchases, detect subscriptions, predict cash flow, suggest budget limits, or answer questions such as “How much did I spend on food delivery last month?”
Automatic categorization is the foundation
Manual budgeting often breaks at the categorization stage. AI models learn merchant patterns and your corrections. A payment to a grocery store becomes food; a streaming charge becomes entertainment; a transfer between your own accounts is excluded from spending. Good categorization is not glamorous, but it is the feature that makes every other insight trustworthy. If categories are wrong, the advice built on them will be wrong too.
Insights instead of raw transactions
A list of 300 transactions is data, not guidance. AI can summarize the story: your transport costs rose because of three taxi trips, your food budget is fine but convenience spending doubled, or a yearly subscription renews next week. These explanations help because money problems are often specific and fixable. You do not need a lecture about “spending less”; you need to know which leak to plug first.
Budgeting That Adjusts to Real Life
Traditional budgets often assume every month is identical. Real life disagrees. Income may vary, fuel prices change, birthdays cluster, and annual bills appear just when you forgot them. AI budgeting tools can adapt by looking at recent patterns and upcoming obligations rather than forcing your life into a fixed template.
Predictive cash-flow warnings
One of the most practical features is forecasting. If rent, a card payment, and an insurance premium all leave your account before payday, an app can warn you while there is still time to move money or delay a purchase. This is less about intelligence in the abstract and more about timing. A warning five days early can prevent an overdraft fee; the same warning after the fact is just bad news.
Flexible goals and automatic saving
Some apps round up purchases, move small amounts when spending is low, or recommend a savings transfer after income arrives. The psychology is sound: saving works better when it is automatic and modest enough to survive. AI can adjust the amount based on predicted bills, but users should keep limits and easy pause controls. Automation should reduce stress, not create a surprise when the app moves money at the wrong moment.
Debt, Bills, and Subscriptions Under Control
Debt becomes harder to manage when due dates, interest rates, and minimum payments are scattered across accounts. AI finance apps can gather these into one timeline, estimate interest costs, and model payoff strategies such as paying the highest-rate balance first or clearing the smallest balance for momentum. The model can show trade-offs; you choose the strategy you can sustain.
Subscription creep is a quiet budget leak
Free trials convert, prices rise, and duplicate services accumulate. AI is good at spotting recurring charges and flagging changes. A monthly review of subscriptions can free surprising amounts of money without touching daily pleasures. The app might find a forgotten app plan, an unused gym add-on, or two cloud storage services doing the same job. Cancelling one repeated charge can be worth more than skipping many small treats.
Bill negotiation and reminders
Some services help identify bills that may be negotiable or alert you before a price increase takes effect. Even when an app cannot negotiate for you, reminders and comparisons are useful. Money management often improves through boring consistency: pay on time, avoid fees, review recurring costs, and keep minimum payments covered while you attack expensive debt.
Investing Features and Their Limits
Many personal finance platforms now include net-worth tracking, retirement projections, or automated investing. AI may help rebalance a portfolio, harvest tax losses where applicable, or explain performance in plain language. These features can be useful, especially for beginners who need a clear dashboard. They also require more caution than budgeting features.
Education is safer than prediction
Be wary of any app that claims AI can predict markets or guarantee returns. Markets are uncertain, and past patterns do not ensure future results. A responsible tool explains risk, fees, diversification, and time horizon. It should help you understand why you own something, not push frequent trading or fashionable assets. If an AI feature encourages urgency, secrecy, or unusually high returns, treat that as a warning sign.
Keep the whole picture in view
Budgeting and investing should not live in separate mental boxes. An app that sees your cash buffer, debts, goals, and investments can help you avoid contradictions, such as investing money you will need next month or keeping expensive card debt while chasing small portfolio gains. Businesses face the same coordination problem at a larger scale, which is why owners use systems described in AI automation for small businesses to connect routine financial tasks instead of juggling disconnected tools.
Privacy and Security Questions to Ask
A finance app asks for access to some of your most sensitive information. Before connecting accounts, check how the service makes money, what data it collects, whether it sells or shares data, how connections are secured, and how you can delete your information. Free is not automatically bad, but you should understand the exchange.
Read-only access and strong authentication
Prefer services that use reputable account-connection providers, support multifactor authentication, encrypt data, and do not ask you to share your bank password directly with unknown parties. Review connected accounts regularly and remove apps you no longer use. A tidy digital life is part of financial safety: fewer forgotten connections means fewer doors into your money.
AI advice can be wrong
Apps can miscategorize income, miss a pending transaction, misunderstand a goal, or produce a confident but flawed explanation. Always check important numbers against your bank or statements. For tax, legal, mortgage, or complex investment decisions, consult a qualified professional. AI can prepare the picture and highlight questions; it should not be the final authority on consequential choices.
How to Choose and Use an App Well
The right app depends on your main problem. If you overspend in a few categories, choose strong budgeting and alerts. If bills surprise you, prioritize cash-flow forecasting. If debt is the issue, look for payoff planning and due-date control. If you mainly want awareness, a clean net-worth and spending dashboard may be enough.
A two-week starter routine
- Connect accounts carefully: start with your main bank and card, then verify balances and categories.
- Fix the top categories: correct food, transport, housing, income, and transfers before fine-tuning small labels.
- Set three alerts: low balance, large purchase, and upcoming bill cluster.
- Review once a week: spend ten minutes checking insights, subscriptions, and next week’s forecast.
- Automate one improvement: a modest savings transfer or extra debt payment you can sustain.
After two weeks, judge the app by behaviour change, not by how beautiful the charts look. Did it prevent a fee, reveal a leak, make saving easier, or help you decide faster? If not, change the settings, simplify the categories, or try a different tool. The best system is the one you will keep using after the novelty fades.
Making the Most of Alerts, Reports, and Coaching
The difference between a helpful finance app and another ignored notification is design. Too many alerts train you to swipe them away. Too few leave the app as a passive record. The sweet spot is a small set of messages tied to action: a bill is larger than usual, a category is likely to exceed its limit, income has arrived and a planned transfer can happen, or a subscription price has changed.
Weekly reports beat daily nagging
A short weekly report can be more effective than constant prompts. Look for a summary that compares this week with your normal pattern, names the top three changes, and shows the next seven days of expected bills. That format respects attention. It also creates a natural moment to decide one adjustment: move a purchase, increase a debt payment, cancel a service, or leave the plan alone because the variation is explained.
Coaching should be specific and kind
Some apps now include chat-style coaching that answers questions about your own data. Used carefully, this can be motivating: “Your food delivery spending rose after late workdays; would a Sunday meal-prep reminder help?” That is better than generic shame about buying coffee. Still, check the numbers behind any coaching claim. Ask what period it used, whether transfers were excluded, and whether a one-off expense distorted the pattern. Good coaching invites a workable experiment, not a personality judgment.
Set rules for how you will respond to insights. For example, any subscription flagged twice gets cancelled or consciously renewed. Any category that exceeds its limit two months in a row gets a new limit based on evidence, not guilt. Any predicted shortfall triggers a transfer before discretionary spending. Rules turn information into a system. Without them, even excellent AI insights become interesting trivia.
Finally, review the app itself every few months. Are the categories still accurate? Has your income pattern changed? Are you paying for premium features you do not use? Has a new account been left unconnected, making the forecast incomplete? A finance assistant is only as good as the picture it sees and the habits you build around it. Maintain the system lightly but regularly, and it will keep earning its place.
Frequently Asked Questions
Are AI personal finance apps safe?
Many established apps use encryption, read-only account connections, and multifactor authentication, but no app is risk-free. Safety depends on the provider’s practices and your habits. Research the company, understand its privacy policy, use strong unique passwords, enable extra login protection, and disconnect services you stop using.
Can an AI budgeting app really save me money?
It can help by exposing spending patterns, warning about bills, finding subscriptions, and automating small savings moves. The savings come from the actions you take after seeing the information. An app cannot create money from nothing, but it can reduce fees, leaks, and forgetfulness that quietly drain a budget.
Should I let an app invest for me automatically?
Automation can be reasonable for long-term, diversified investing when fees are clear and the risk level matches your goal and timeline. It is not suitable for money needed soon or for strategies you do not understand. Avoid tools promising predictions or guaranteed profits, and review automated settings regularly.
The Bottom Line
AI personal finance apps are most valuable when they turn messy transactions into timely, understandable guidance. They can categorize spending, forecast tight weeks, control subscriptions, support debt payoff, and automate saving. Their limits are just as important: protect your data, verify important numbers, and ignore any promise of easy market-beating returns. Use AI to make your financial life clearer and calmer, while you remain the person who decides what the money is for.