Property has created more quiet fortunes than almost any other asset, but it has a stubborn entry fee: you need a large deposit, a mortgage, and the patience to deal with tenants and repairs. Real estate investment trusts exist to remove that barrier. With REITs explained properly, you will see they are simply companies that own income-producing property — offices, apartments, warehouses, hospitals, shopping centres — and let you buy a small slice of the whole portfolio with a single stock-market purchase. You get exposure to rental income and property values without ever unblocking a drain. This guide covers how REITs work, how they pay you, the main types, their genuine risks, and how they might fit alongside the rest of your investments.
What Is a REIT?
A REIT (pronounced “reet”) is a company that owns, operates, or finances real estate that produces income. Its special legal status is the key to everything else. In most countries that offer the structure, a REIT pays little or no corporate tax — but only if it follows strict rules, the most famous being that it must distribute the large majority of its taxable income to shareholders as dividends. In the United States, that requirement is at least 90%.
This one rule shapes the entire character of REIT investing. Because the company cannot hoard its rental profits, shareholders receive a steady stream of income. Because it cannot retain much cash, a REIT that wants to grow must regularly raise new money from investors or borrow — which makes management discipline and interest rates unusually important, as we will see.
How the Money Flows
Picture a REIT that owns fifty apartment buildings. Thousands of tenants pay rent each month. The REIT uses that rent to cover property costs, staff, maintenance, and interest on its loans. What remains flows out to shareholders as dividends. Meanwhile, if the buildings rise in value, the share price tends to reflect that too. Your return therefore comes from the same two sources as a landlord’s: rental income and property appreciation — minus the landlord’s workload.
How REITs Pay You
Dividends are the headline attraction. REIT dividend yields are often noticeably higher than the average stock’s, precisely because the law forces profits out the door. Payments are typically quarterly, sometimes monthly. For income-focused investors, that regularity is valuable: it resembles the rent cheque a landlord receives, but it arrives without a single phone call about a broken boiler.
The second source of return is growth. A well-run REIT increases rents over time, develops new properties, and buys undervalued buildings, growing both its income per share and its property value. Historically, total returns from diversified REIT indexes have been competitive with the broader stock market over long periods, though the path is rarely smooth and past performance never guarantees future results.
What Drives a REIT’s Dividend?
Investors watch a metric called funds from operations, or FFO, rather than ordinary accounting profit, because property depreciation distorts normal earnings figures. A healthy REIT grows its FFO per share steadily, pays out a sustainable portion of it, and keeps its debts manageable. A dividend that grows slowly and reliably is worth far more than a spectacular yield funded by borrowing.
The Main Types of REITs
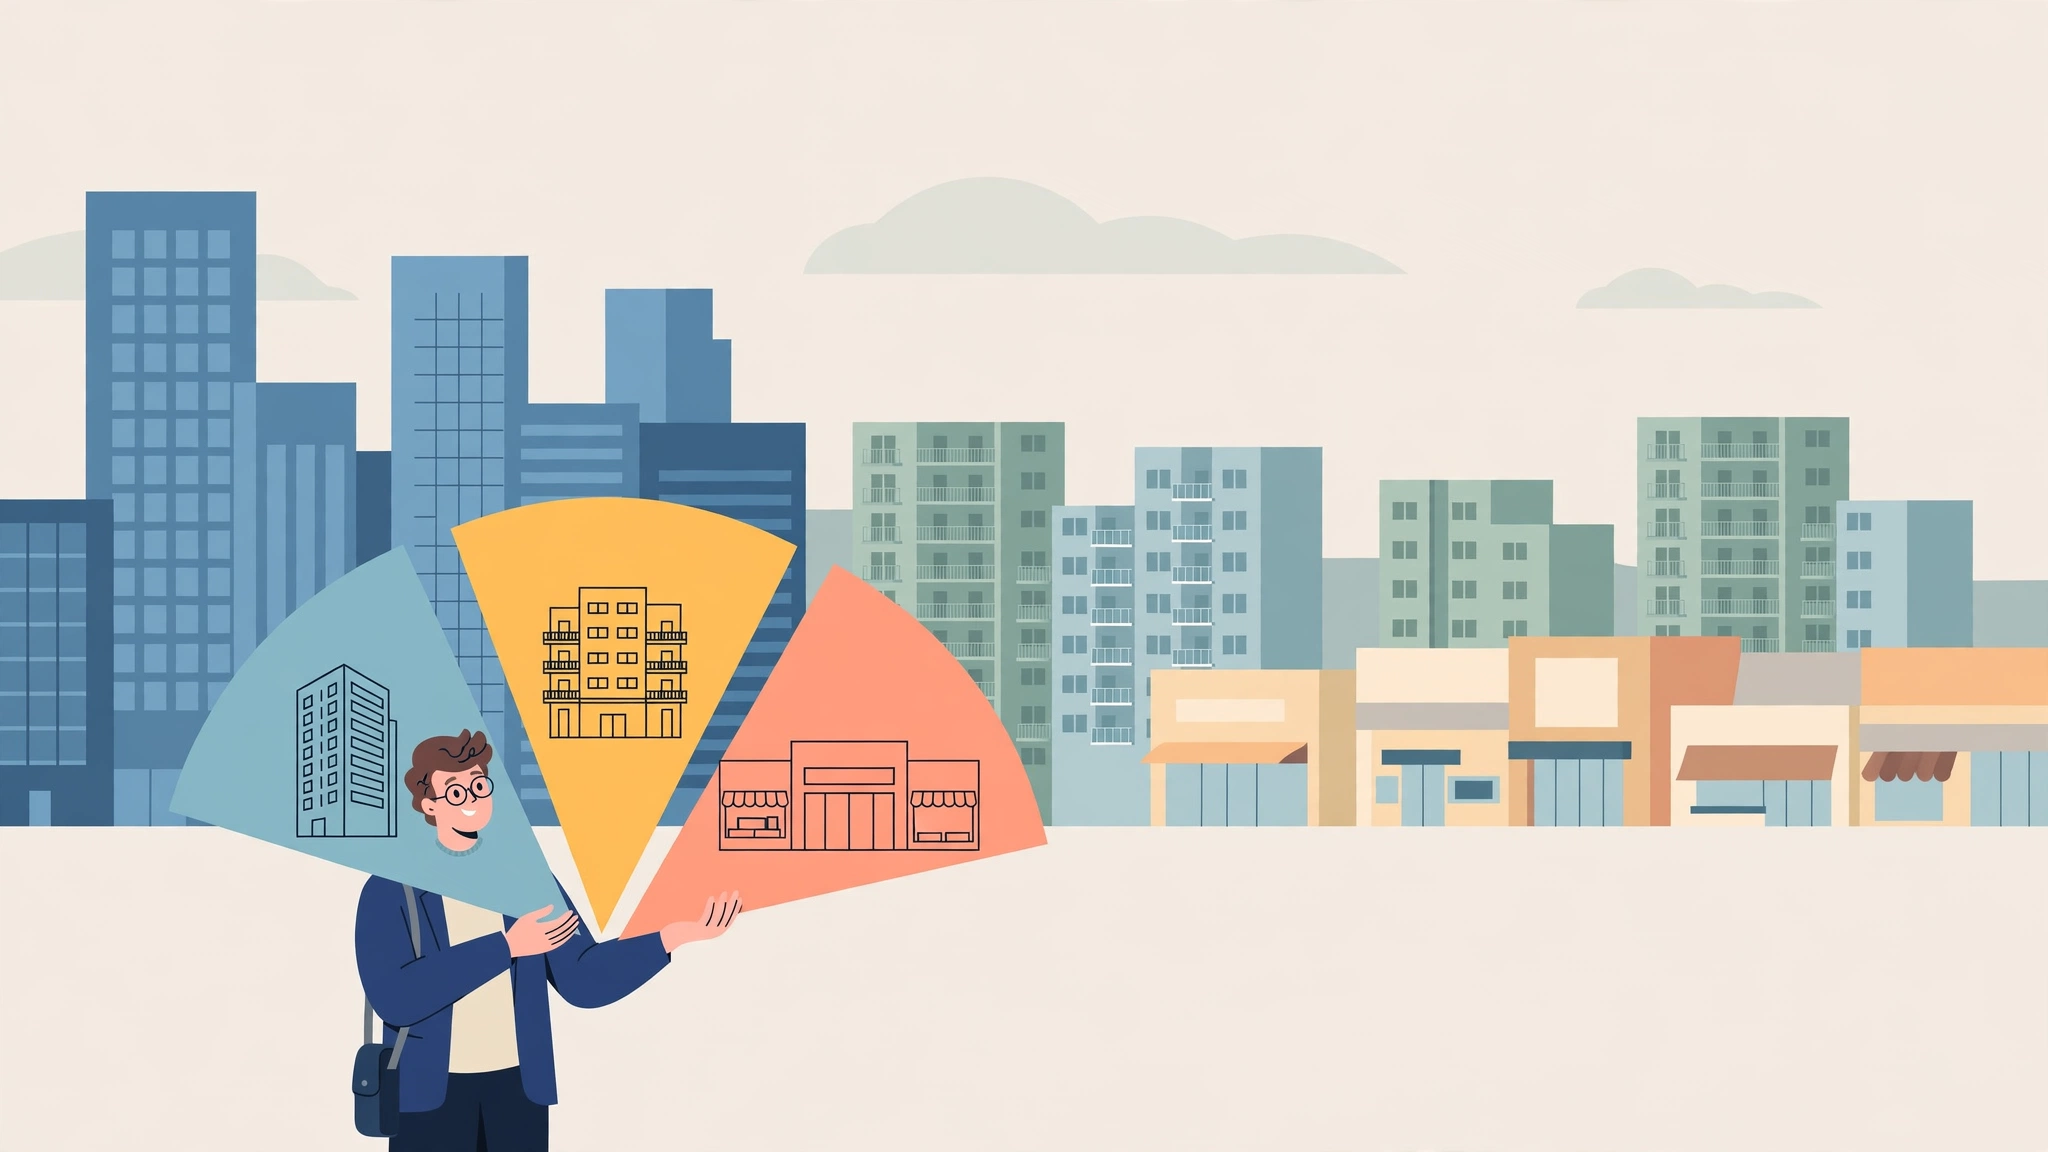
“REIT” is a family name, not a single product. Different types own very different properties and respond to different economic forces, so the type matters as much as the label.
By What They Own
- Residential REITs own apartment buildings and rental housing. Demand follows population and jobs; people always need somewhere to live.
- Retail REITs own shopping centres and high-street stores. They thrive when consumer spending is strong and tenants are healthy.
- Office REITs own office towers. Remote and hybrid work have made this sector more uncertain than it once was.
- Industrial REITs own warehouses and logistics centres — the backbone of online shopping — and have benefited from e-commerce growth.
- Healthcare REITs own hospitals, clinics, and senior housing, tied to demographics and healthcare demand.
- Specialty REITs own everything from data centres and mobile-phone towers to timberland, prisons, and self-storage units.
By How They Make Money
- Equity REITs own physical property and earn rent. These are the classic type most people mean by “REIT.”
- Mortgage REITs do not own buildings; they lend money to property owners or buy mortgage-backed securities, earning the spread between borrowing and lending rates. They are more complex and considerably more volatile.
- Hybrid REITs combine both approaches.
Beginners are usually better served by equity REITs, whose business model — own buildings, collect rent — can be understood at a glance.
The Advantages of REITs
Several features make REITs genuinely useful rather than merely convenient.
- Low entry cost: you can start with the price of a single share or a small fund contribution instead of a property deposit.
- Diversification: one REIT may own hundreds of properties across many cities; a REIT fund owns many REITs. A single bad tenant or empty building barely registers.
- Liquidity: listed REITs trade on stock exchanges, so you can sell in seconds. Selling an actual building takes months.
- Professional management: acquisitions, leases, and maintenance are handled by specialists.
- Income: the mandatory payout structure produces higher, more regular dividends than most stocks.
The Risks You Should Respect
REITs are stocks, not savings accounts, and their prices move accordingly.
Interest Rate Sensitivity
REITs borrow heavily to buy property, so rising interest rates squeeze them twice: loan costs climb, and their dividends look less attractive next to safer bonds. REIT prices often fall when rates rise, even if the underlying buildings are performing fine.
Property Market Risk
Vacancies rise in recessions. Tenants negotiate lower rents or go out of business. A REIT concentrated in one struggling sector — offices in an era of remote work, for example — can suffer for years. Sector and geographic diversification are your main defences.
Leverage and Management Risk
Debt magnifies both gains and mistakes. Because REITs must pay out most income, they depend on capital markets to fund growth; when markets freeze, growth stalls. And unlike a passive index of buildings, each REIT is a managed company whose leaders can overpay for acquisitions. You are trusting their judgement.
Tax Treatment
In many countries REIT dividends are taxed as ordinary income rather than at lower dividend or capital-gains rates, which can reduce after-tax returns in taxable accounts. The rules vary by country and account type, so check your own situation rather than assuming.
REITs vs Owning Rental Property Directly
Direct ownership offers control: you choose the property, set the rent, and can improve it with your own effort. It also concentrates your wealth in one building on one street, demands real work, and ties up a large sum. REITs offer the opposite profile: no control and no work, tiny minimums, instant diversification, and easy selling. Many investors eventually use both, but for a first step into property income, REITs are the simpler classroom. If you are weighing property against the stock market more broadly, our investing for beginners guide explains how property fits into a starter portfolio.
How to Invest in REITs
You have three practical routes. First, buy shares in individual listed REITs through a normal brokerage account, researching each company’s properties, debts, and dividend record. Second, buy a REIT index fund or ETF, which spreads your money across dozens of REITs in one purchase — the simplest route for most beginners. Third, check whether your existing broad index funds already include REITs; large stock indexes typically hold a small REIT allocation, so you may own some already without realising it.
Whatever route you choose, most advisers treat REITs as one slice of a diversified portfolio — often somewhere around 5–15% — rather than the main course. They complement stocks and bonds; they do not replace them.
How to Judge a REIT Before You Buy
If you do look at individual REITs rather than a fund, a short checklist separates the solid landlords from the fragile ones. Start with the properties themselves: what type are they, where are they, and how full are they? Occupancy rates above the mid-90s suggest healthy demand, while falling occupancy is an early warning sign. Next, look at the tenants and leases. Long leases with strong tenants — supermarkets, logistics firms, healthcare providers — produce steadier income than short leases with struggling retailers, and a REIT that depends on one giant tenant is riskier than its yield implies.
Then examine the balance sheet. How much debt does the REIT carry relative to the value of its properties and its earnings? Conservative REITs borrow moderately and spread their loan maturities over many years, so no single year forces them to refinance everything at whatever rates prevail. Check whether the dividend is comfortably covered by funds from operations, with room to spare; a payout that consumes every penny of FFO leaves nothing for repairs, improvements, or bad years, and often ends in a dividend cut. Finally, look at the track record: has FFO per share grown steadily across a full economic cycle, including a recession? A management team that protected the dividend and the balance sheet through hard times has shown you the only evidence that really counts.
None of this requires professional tools — REITs report occupancy, debt, and FFO prominently because investors demand them. But it does require reading, which is exactly why a diversified REIT index fund remains the sensible default for anyone who does not enjoy that work.
Frequently Asked Questions
Do REITs pay monthly dividends?
Some do, but most pay quarterly. The frequency depends on the individual REIT. REIT funds usually pass dividends through on their own schedule, often quarterly.
Are REITs good for beginners?
They can be, especially through a diversified REIT index fund. The business model is easy to understand, but beginners should expect stock-like price swings and should not buy solely for a high advertised yield.
Can REITs lose value in a recession?
Yes. Falling occupancy, weaker tenants, and tighter credit can reduce both REIT income and share prices during downturns. Their dividends have been cut in past recessions, though diversified, conservatively financed REITs have generally weathered storms better than leveraged ones.
REITs Around the World
Although the structure began in the United States in 1960, versions of it now exist in more than forty countries, including the United Kingdom, Canada, Australia, Japan, Singapore, and much of Europe. The details differ — minimum payout rules range from 75% to 100% of income, and tax treatment varies — but the core bargain is the same everywhere: tax transparency in exchange for distributing rental profits to investors. For investors outside the US, domestic REITs may offer friendlier tax handling than foreign ones, and global REIT funds exist for those who want property exposure across several markets at once. Whichever market you choose, the same questions apply: what properties, how much debt, and is the dividend covered by real rental income?
The Bottom Line
REITs turn property — the most hands-on of investments — into something you can buy like a share: rental income flowing out as dividends, professional managers doing the work, and diversification across hundreds of buildings. In exchange you accept stock-market volatility, sensitivity to interest rates, and the judgement of a management team. For investors who want real estate income without buying property, that is a fair and useful trade — taken as one measured slice of a broader plan.
This article is educational content only and is not personalized financial advice. Consider your own circumstances, or speak with a qualified adviser, before making investment decisions.