If you have ever wondered how ordinary people invest in the whole stock market without picking stocks one by one, the answer is usually an index fund. Ask any experienced investor what is an index fund and they will describe the same simple idea: a single fund that holds every company in a market index, giving you instant diversification for a very low fee. This complete beginner’s guide explains how index funds work, what they cost, their real benefits and risks, and how to buy your first one step by step.
Start with the Index
An index is a list of companies that represents a market, together with a rule for how much weight each company gets. The S&P 500 tracks 500 large American companies. The FTSE 100 tracks 100 large UK companies. Global indexes track thousands of companies across many countries. When newsreaders say “the market rose today,” they usually mean an index rose. You cannot buy an index directly, because it is just a calculation. An index fund is the product that copies it.
So, What Is an Index Fund?
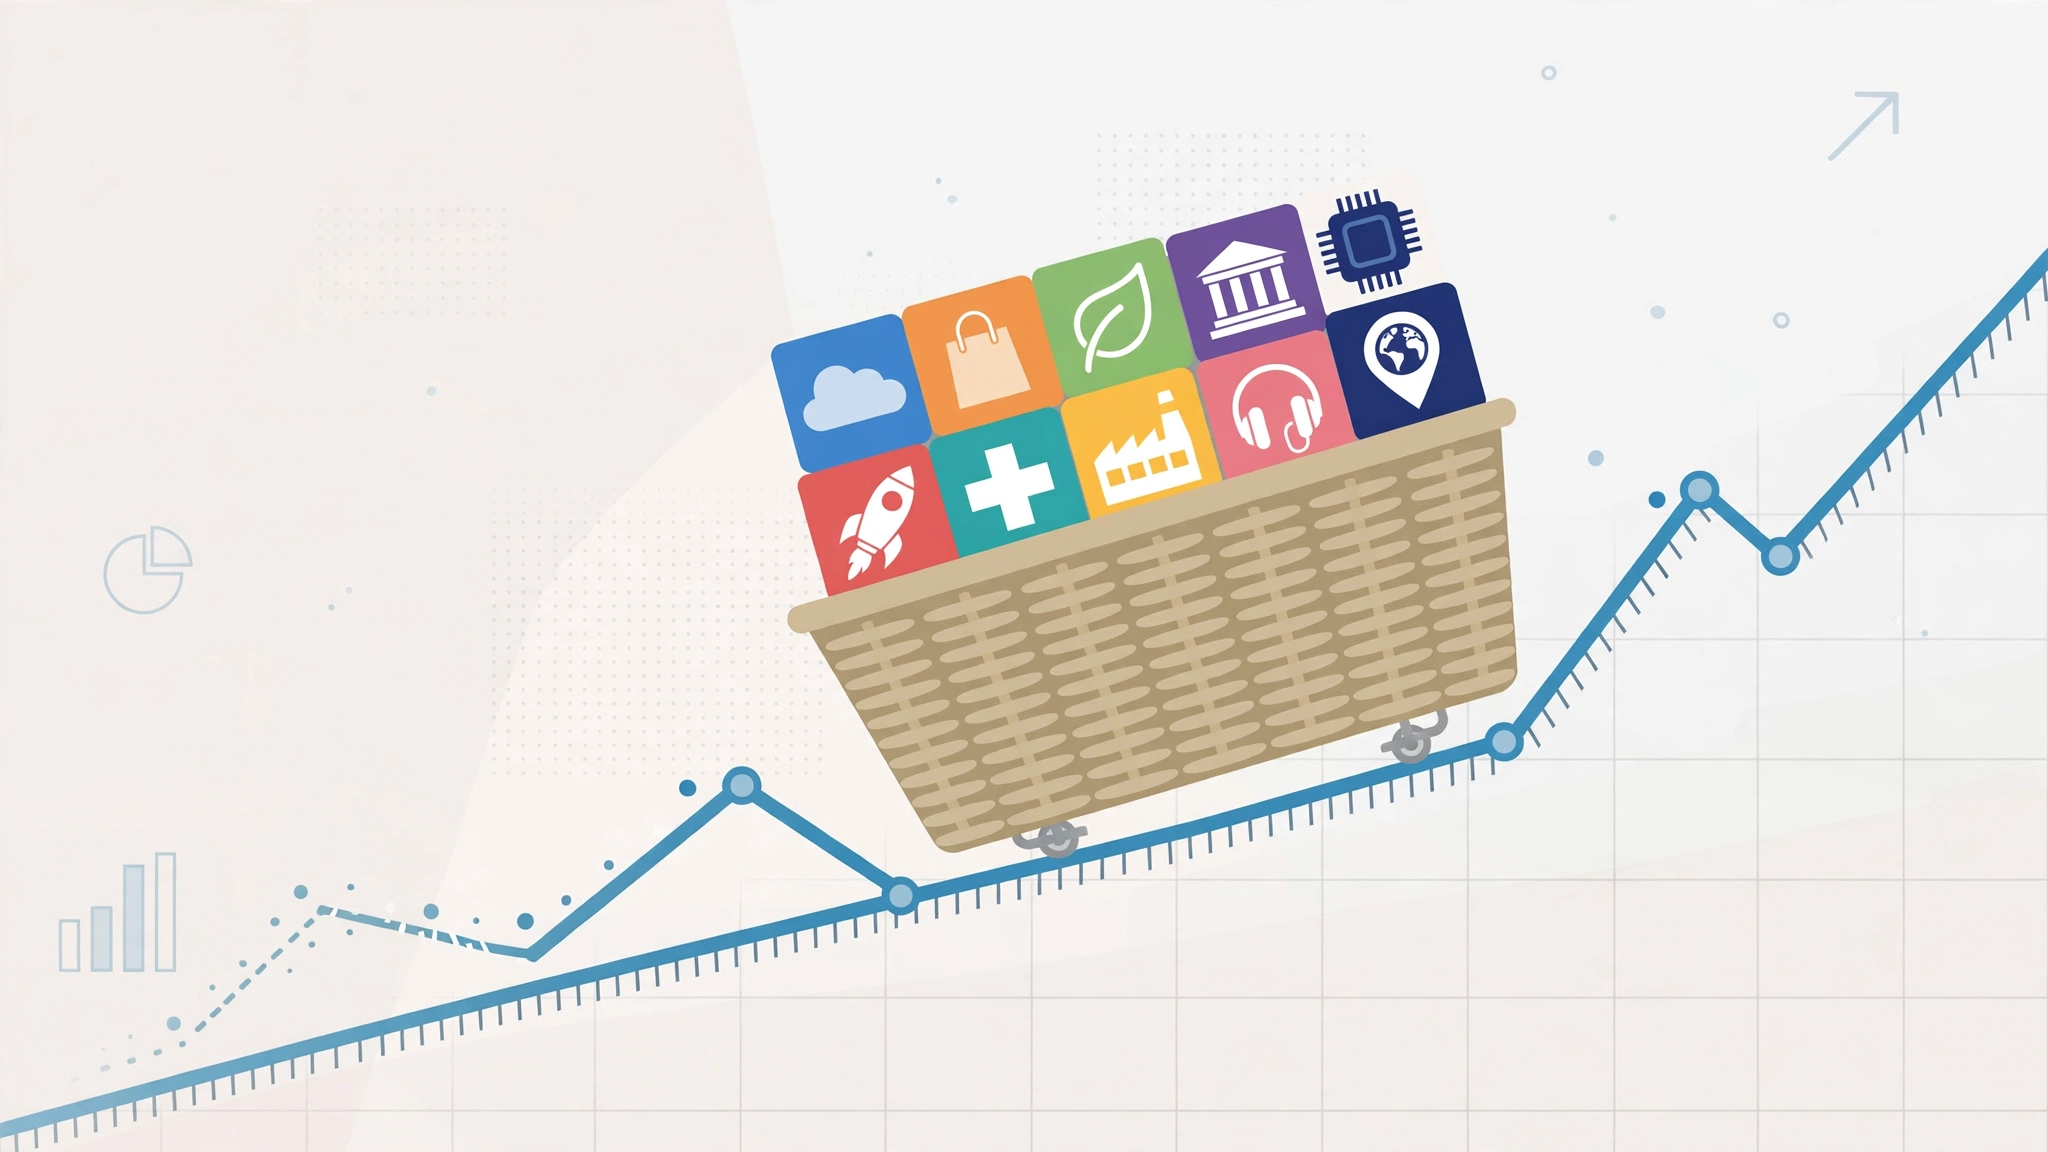
An index fund is a pooled investment that buys all, or nearly all, of the shares in its target index, in the same proportions. If the index gives a company a 3 percent weight, the fund holds about 3 percent of its money in that company. When the index changes, the fund adjusts to match. The fund does not try to predict winners or avoid losers; it simply owns the market and accepts the market’s return, minus a small fee.
A Simple Analogy
Imagine buying one small slice of every dish at a buffet instead of betting your dinner on a single plate. Some dishes will disappoint, a few will be excellent, and overall you get the average of the whole spread, which, in investing, has historically been a satisfying meal. Stock picking is betting on one plate. An index fund is the buffet.
How Index Funds Make (and Lose) Money
Your return comes from two sources. First, the companies in the index can grow in value, lifting the fund’s price. Second, many companies pay dividends, which the fund either pays out to you or reinvests, depending on the version you choose. You lose money when the overall market falls, which happens regularly in the short term. An index fund does not protect you from market declines; it guarantees only that you will get approximately the market’s return, for better and worse, at very low cost.
Index Funds vs ETFs vs Actively Managed Funds
Index Mutual Funds and Index ETFs
Index funds come in two wrappers. A traditional index mutual fund is priced once a day, and you buy it in currency amounts through a provider. An index ETF holds the same kind of portfolio but trades on an exchange throughout the day like a share. The practical differences are small for long-term investors: minimum investments, how you buy, and sometimes tiny cost differences. Both are legitimate ways to own the same idea.
Actively Managed Funds
An active fund employs managers to research and choose investments, aiming to beat the index. This costs more, and over long periods most active funds in most categories have underperformed their index after fees, according to long-running industry scorecards. Some managers do succeed, but identifying them in advance is notoriously hard. This is why index funds are the default recommendation for most beginners, a point we also make in our broader investing for beginners guide.
The Real Benefits
- Instant diversification: one purchase can hold hundreds or thousands of companies across sectors and, for global funds, countries.
- Very low fees: broad index funds commonly charge 0.03 to 0.25 percent per year, a fraction of typical active fees, and the saving compounds in your favor.
- Simplicity: no research, no monitoring of individual companies, no timing decisions. A monthly contribution can run on autopilot.
- Transparency: you always know what you own, because the index is public.
- Reliable relative performance: you will not beat the market, but you will not trail it by much either, which quietly places you ahead of most investors over time.
The Honest Risks and Limits
- Market risk: when the whole market falls 25 percent, your fund falls about 25 percent. Diversification removes single-company risk, not market risk.
- No downside protection: the fund holds falling companies all the way down if they remain in the index.
- Concentration inside big indexes: capitalization-weighted indexes give the largest companies the biggest weights, so a handful of giant firms can dominate returns.
- Tracking difference: funds follow their index closely but not perfectly; fees and trading create a small gap.
- Boredom: the strategy is deliberately uneventful, which some investors find hard to stick with when exciting stories are elsewhere.
What Index Funds Cost
The main ongoing charge is the expense ratio, the yearly percentage taken from the fund to run it. On a 10,000 investment, a 0.1 percent expense ratio costs about 10 a year; a 1 percent active fee costs about 100, every year, growing as your pot grows. You may also pay platform or account fees depending on your provider, and ETF trades can involve small spreads between buying and selling prices. Total cost is one of the few factors in investing that is both predictable and within your control, which is why this guide keeps returning to it.
How to Buy Your First Index Fund: Step by Step
- Step one: sort your foundations first, an emergency fund and no expensive debt, so you can invest money you will not need for years.
- Step two: choose a reputable, regulated provider or broker available in your country, and open the appropriate account, using any tax-advantaged options your country offers for long-term investing.
- Step three: pick your index. Many beginners start with one global equity index fund for worldwide diversification, or a home-market index if they prefer simplicity.
- Step four: decide between the mutual fund and ETF version based on minimums and convenience, and check the expense ratio.
- Step five: set up an automatic monthly contribution you can sustain, and choose the accumulating version if you want dividends reinvested automatically.
- Step six: review once or twice a year. Rebalance only if your overall plan changes, not because of headlines.
The Main Types of Index Funds
Broad Market and Large-Cap Funds
These track major indexes such as the S&P 500 or a total-market index covering large, medium, and small companies together. They are the most common starting point, offering the core of a national market in one holding.
Global and International Funds
Global funds hold companies from many countries in a single product, while international funds cover markets outside your home country. A global fund is the simplest route to worldwide diversification, removing the need to guess which country’s market will perform best, a guess even professionals routinely get wrong.
Bond Index Funds
Indexing works for bonds too. Bond index funds hold diversified baskets of government and corporate bonds and typically play a stabilizing role in a portfolio, producing income with smaller swings than shares. Their returns are usually lower over long periods, which is the price of that calm.
Sector and Thematic Funds
These track slices of the market, such as technology, healthcare, or clean energy. They are still index funds, but they are the opposite of diversified: a concentrated bet on one theme. Beginners should treat them, at most, as small additions around a broad core, never as the core itself.
Accumulating vs Distributing: One Choice to Know
Many index funds come in two versions. A distributing fund pays dividends out to you as cash. An accumulating fund automatically reinvests dividends inside the fund, so your holding compounds without you lifting a finger. For long-term investors who do not need income yet, accumulating is usually the simpler choice. For those drawing an income, distributing provides regular payments. Tax treatment of the two can differ by country, so check your local rules or ask an adviser if the amounts become significant.
A Brief History: How Index Funds Went Mainstream
The first index fund for ordinary investors launched in the 1970s and was widely mocked on Wall Street as a surrender, a fund for people who had given up trying to win. The criticism missed the point: the fund’s founder argued that after costs, the average professional investor could not beat the market they collectively created, so owning the market cheaply was the rational choice. Decades of data since then have largely supported that argument, and index funds have grown from a curiosity into the default building block of retirement accounts around the world. The mockery has mostly stopped. Today, the debate is no longer whether indexing works, but how to use it well: which indexes to own, in what proportions, and how to behave when markets test your patience, because the fund supplies the strategy, but only you can supply the discipline.
Common Questions Beginners Ask Before Buying
Two hesitations appear again and again. The first is whether to invest a lump sum at once or spread it over months. Historically, investing available money immediately has won more often than waiting, simply because markets rise more often than they fall, but spreading contributions can feel safer and helps some investors actually start. Either approach, followed consistently, beats indefinite delay. The second hesitation is which single fund to choose when several look similar. When expense ratios are all low and the indexes overlap heavily, the differences are minor; a global or broad national fund from any major provider will do the job. Beginners often spend weeks on this choice and minutes on the far more important ones: how much to contribute, and whether they can hold through a fall. Get the big decisions right and the small ones mostly take care of themselves.
Frequently Asked Questions
How much money do I need to start an index fund?
Often very little. Many mutual fund providers accept small monthly contributions, and ETFs can be bought one share at a time, sometimes fractionally. The habit of contributing regularly matters far more than the starting amount.
Are index funds safe?
They are diversified and transparent, but they are not safe in the sense of being guaranteed. Their value falls when markets fall. They are best suited to goals five or more years away, where history suggests time smooths the ride, without ever promising a result.
Index fund or ETF: which should a beginner choose?
Either can be right. Choose the mutual fund if you want automatic monthly investing in exact amounts with once-a-day pricing. Choose the ETF if your platform offers cheap trading and you are comfortable buying during market hours. Low cost and broad diversification matter more than the wrapper.
The Bottom Line
An index fund is a simple, low-cost way to own the whole market instead of guessing its winners. It offers instant diversification, minimal fees, and a strategy you can automate and actually stick with. It will fall when markets fall, and it will never make you rich quickly, but over long periods, capturing the market’s return at tiny cost has proven a powerful and reliable approach for ordinary investors. For most beginners, it is not just a good first investment; it is a sensible permanent core.
This article is educational content only and is not personalized financial advice. Consider your own circumstances and, if needed, speak with a qualified financial adviser before making investment decisions.